When Income Changes Before the House Does
Should You Sell Your House After Losing a Job?
A job loss does not automatically mean the house has to be sold. The better first question is whether the property still fits the household budget if income is lower for the next several months.
Some homeowners have enough savings, severance, unemployment income, or other household earnings to keep making the mortgage while looking for another job. Others discover that the mortgage, property taxes, insurance, utilities, repairs, and other ownership costs are using money they need for more immediate expenses.
If you are searching for ways to sell my house fast after losing a job, it can help to compare your options before missed payments determine the timeline for you. A direct offer from Green Door Home Buyers is one number you can compare with keeping the property or listing it traditionally.
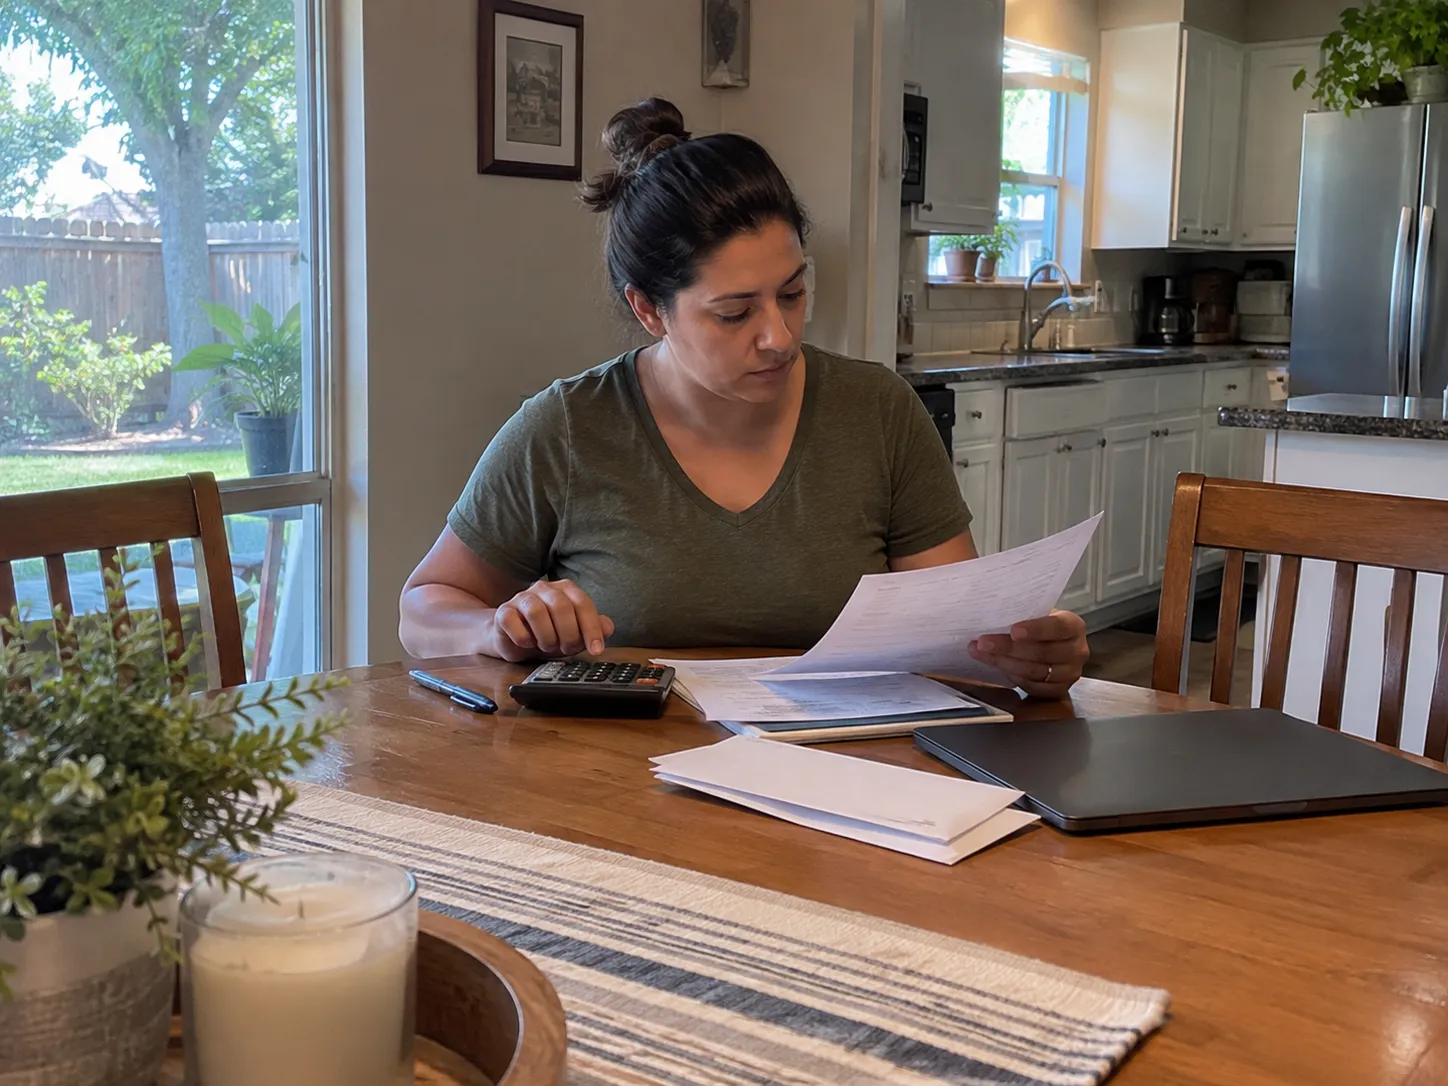
The best choice depends on whether the income change appears temporary, how much cash is available to cover housing costs, the amount of equity in the property, and what the next housing arrangement would cost. Selling quickly simply to eliminate a mortgage payment can create a new expense if the replacement rental or home is not actually cheaper.
Treat the house as one part of the household budget rather than making the decision from the mortgage payment alone.
Before Choosing a Selling Method
Calculate How Much Time the Current Housing Budget Gives You
01
Check Available Monthly Income
Start with income that is actually available now rather than what you expect a future job to pay. Include other household earnings and any benefits or severance that you know will be received.
The purpose is not to build a perfect financial plan. It is to see whether the current housing payment can realistically continue while employment is uncertain.
02
Measure the Full Cost of the House
The mortgage is only part of ownership. Property taxes, homeowners insurance, HOA dues, utilities, maintenance, lawn care, repairs, and other recurring expenses can materially change the monthly total.
An older Houston-area house may also have upcoming repair costs that are not reflected in the normal monthly budget.
03
Compare the Cost of Moving
Selling removes the current home’s expenses, but it does not remove the need for housing. Estimate rent, another mortgage, deposits, moving expenses, storage, utilities, and transportation at the place you would live next.
A sale makes more financial sense when the replacement plan actually reduces or better fits the new budget.
Do Not Wait for the First Missed Payment to Ask Questions
Contact Your Mortgage Servicer if the Payment Is Becoming Difficult
Homeowners who are worried about making a mortgage payment should contact their mortgage servicer directly. Depending on the loan and circumstances, the servicer may have mortgage-assistance or loss-mitigation options available.
Forbearance is one possible form of assistance. It may temporarily pause or reduce required payments, but it does not erase the money that is owed. Loan modifications or other arrangements may also be available depending on the mortgage and hardship.
A HUD-approved housing counselor can also help homeowners understand mortgage and foreclosure-prevention options. Green Door Home Buyers is a real estate buyer, so we cannot determine which mortgage-assistance program you qualify for or advise you to choose one over another.
Have Your Loan Information Ready
Before calling the servicer, have your mortgage statement available and be prepared to explain why household income changed, whether the problem appears temporary or longer term, and what you can currently afford.
Getting those answers does not commit you to keeping the house. It gives you another option to compare with selling.
The Same Job Loss Can Lead to Different Housing Decisions
When Keeping the House May Work and When Selling May Be Worth Considering
The Income Loss Looks Temporary
Keeping the property may be reasonable when there is enough savings or other income to cover the home while you search for work and the house remains affordable once employment resumes.
The Mortgage No Longer Fits
Selling deserves a closer look when making the payment requires repeatedly drawing down savings or falling behind on other essential expenses with no clear recovery point.
A New Job Could Require a Move
A job search may expand beyond Houston. If relocation is realistic, compare the cost of continuing to carry the property with selling before or after accepting a position elsewhere.
The House Needs Expensive Work
An aging roof, HVAC system, foundation concern, plumbing issue, or other repair can change the calculation when household income has already declined.

Repairs Can Compete With More Important Expenses
Think Carefully Before Spending Savings to Prepare the House for Sale
Traditional advice often tells sellers to repair, update, paint, stage, and improve a property before putting it on the market. That strategy can make sense when the work is affordable and is likely to improve the seller’s net result.
After a job loss, spending cash on improvements deserves a different calculation. Money used for a kitchen update, flooring, exterior repairs, or landscaping is money that is no longer available for mortgage payments, health insurance, moving expenses, or everyday household costs.
Get realistic repair estimates before assuming that renovating is required to sell.
Green Door Home Buyers buys houses in as-is condition. A direct offer accounts for the property’s present condition rather than requiring the seller to finish repairs before a purchase can be considered.
That does not mean an as-is offer will always produce the highest sale price. It gives you a second scenario to compare with spending money on the house and pursuing a retail listing.
Home Equity Can Create Options
Know What You May Actually Walk Away With
A job loss may create pressure to reduce expenses, but urgency should not replace understanding the property’s equity. Start with a realistic estimate of value and subtract mortgages and other liens that would need to be addressed at closing.
The remaining amount is not automatically the final proceeds. The selling method can add commissions, repairs, concessions, carrying expenses, and other transaction costs. Compare estimated net proceeds rather than just comparing sale prices.
Why This Matters Before Payments Are Missed
A homeowner with meaningful equity may have several ways to use the property to change the household budget.
Understanding those options earlier generally provides more information for comparing a sale, mortgage assistance, relocation, or continuing to own the property.
Compare the Complete Transaction
Listing vs. Selling Directly After a Job Loss
Traditional Market Listing
A traditional listing may be worth considering when the house is already market-ready, there is enough financial runway to keep carrying it, and you want maximum exposure to retail buyers.
The process can include preparation, photos, showings, inspection negotiations, appraisal, and buyer financing. A strong property and adequate time can make those steps worthwhile.
Estimate the likely net proceeds after repairs, commissions, concessions, seller expenses, and the cost of continuing to own the property while it is marketed.
The highest projected sale price is most useful when the homeowner can realistically afford the time and expense required to pursue it.
Direct Sale to Cash Home Buyers
A direct sale may be worth comparing when lowering ongoing housing expenses is a priority, the house needs work, or you would prefer not to spend available savings preparing the property for market.
Green Door Home Buyers is the buyer rather than an agent listing the home for someone else. We buy houses in their current condition, so there is no need to complete renovations simply to request an offer.
The site’s direct-purchase model does not involve an agent commission, and Green Door Home Buyers states that it covers the real estate closing costs associated with its purchase.
There is no obligation to accept the offer. It can simply give you another set of numbers to compare with listing or keeping the property.
What if You Are Already Behind on the Mortgage?
Job loss and foreclosure are related, but they are not the same search intent. Losing income does not mean a foreclosure has started, and homeowners should not assume that one late or difficult payment produces an immediate sale of the property.
If payments have already been missed, contact the mortgage servicer and determine the actual loan status. Ask what amount is due, whether a foreclosure process has begun, what notices have been issued, and what loss-mitigation options may still be available.
If foreclosure activity is already involved, timing becomes more important. Our Houston foreclosure page addresses that situation in more detail.
A home buyer can tell you what it is willing to pay for the property. Your mortgage servicer is the source for the loan status, and a HUD-approved housing counselor or qualified attorney can help with questions outside the buyer’s role.
Do Not Guess About the Deadline
Financial pressure can make every date feel urgent. Use the actual mortgage statement, notices, and information from the servicer instead of assuming that the home has to be sold immediately.
Once you know the real loan status, you can compare your available options using an accurate timeline.
Employment Changes Affect Homeowners Across Greater Houston
Selling a House After Job Loss in the Houston Area
Houston’s size means a job change can affect housing decisions in several ways. A homeowner may be searching for new work within the metro, considering a position on the other side of the region, or looking outside Texas entirely.
Green Door Home Buyers purchases properties throughout Houston and surrounding primary markets including Spring, Conroe, Baytown, Friendswood, Galveston, and League City.
A job loss does not change the property’s local market value by itself. Location, condition, comparable sales, repairs, and current buyer demand still matter. What changes is the homeowner’s reason for evaluating the property and how long carrying costs remain comfortable.
You can learn more about the company on our About Green Door Home Buyers page, read Houston homeowner reviews, or review the cash home buying FAQs before deciding whether to request an offer.
Gather Information Before Making the Housing Decision
A Practical Order for Evaluating a Sale After Job Loss
1
Understand the Mortgage
Confirm the current payment, loan balance, payment status, and any assistance options available through the mortgage servicer.
2
Understand the Property
Estimate current value, known repairs, liens, likely selling expenses, and the amount of equity that may remain after a sale.
3
Compare Real Selling Options
Compare keeping the house, listing traditionally, and a direct as-is offer using the actual costs and timelines that apply to your household.
You Do Not Have to Decide Before Getting an Offer
Requesting a cash offer does not mean you have decided to sell. It gives you another piece of information while you evaluate employment, mortgage assistance, household expenses, and the value of the property.
A homeowner may decide that keeping the house makes sense once another job is secured. Someone else may determine that reducing the monthly housing obligation now is more useful than continuing to carry the property while searching for work.
The purpose of comparing options early is to make that decision while you still have choices rather than waiting until financial pressure makes the decision for you.
See What the House Could Sell for As-Is
Compare a Houston Cash Offer After a Job Loss
If household income has changed and selling is one of the options you are considering, Green Door Home Buyers can evaluate the property in its current condition and explain our direct buying process.
Call (832) 843-2780 or request a cash offer online. You can compare the offer with keeping the house or listing traditionally and decide which route fits your current finances and housing plans.